The Bank of Ghana (BoG) has announced plans to introduce a Credit Risk Management Directive to strengthen lending practices, improve loan recovery and tackle rising non-performing loans (NPLs), particularly within the savings and loans sub-sector.
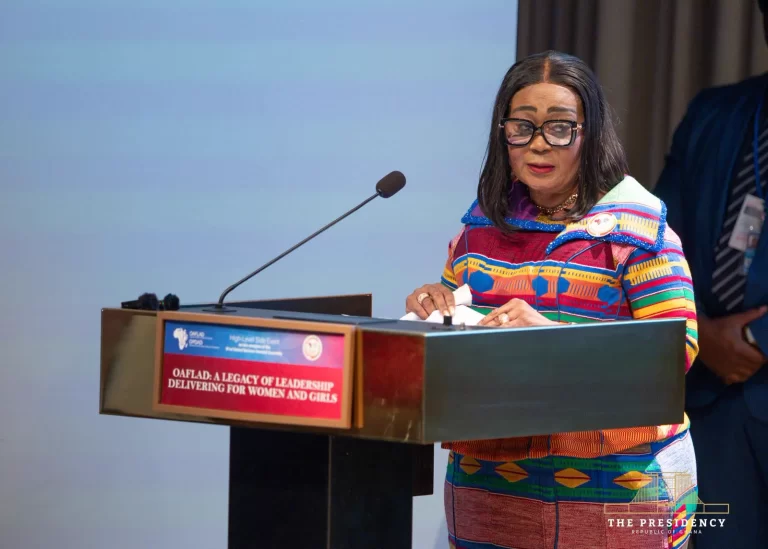
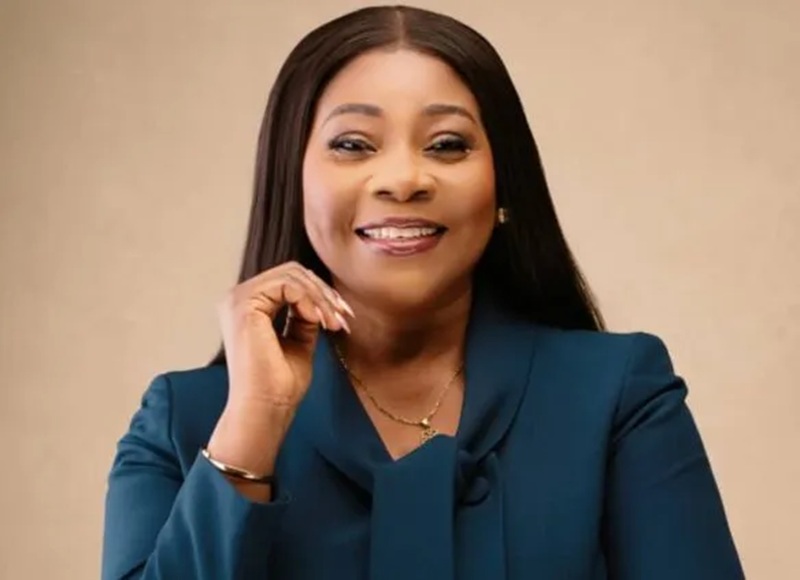
Second Deputy Governor of the Bank of Ghana, Matilda Asante-Asiedu, announced the planned directive on Wednesday, October 7, 2026, at the commissioning of the new head office of Advans Ghana Savings and Loans in Dzorwulu, Accra.
She said the directive would require regulated financial institutions (RFIs) to establish robust frameworks for identifying, assessing, monitoring and managing credit risks throughout the lending process.
According to her, the framework would cover credit underwriting, loan administration, risk measurement, monitoring and recovery, with the objective of preventing the accumulation of bad debts and strengthening the financial sector.
“This directive aims to ensure that Regulated Financial Institutions (RFIs) develop and implement appropriate frameworks for managing their credit risk by establishing a robust credit risk environment; a sound credit-underwriting process; and maintaining appropriate credit administration, measurement, monitoring, and recovery processes and functions,” she stated.
The proposed directive is expected to establish clearer requirements for assessing borrowers’ creditworthiness, managing lending risks and monitoring loans to ensure that financial institutions adopt more effective approaches to credit management.
The announcement comes as the savings and loans industry faces mounting pressure to improve the quality of its loan portfolios, following a deterioration in its non-performing loan ratio despite an improvement in the broader banking industry.
Asante-Asiedu disclosed that the banking industry’s NPL ratio had declined to 16.1 per cent at the end of June 2026, compared with more than 23 per cent a year earlier.However, the savings and loans sub-sector recorded an increase in its NPL ratio from 15.35 per cent in June 2025 to 19.44 per cent in June 2026.
The figures highlight the challenges confronting the sub-sector as regulators intensify efforts to ensure that financial institutions manage credit responsibly and recover loans granted to customers. The Bank of Ghana expects regulated financial institutions to reduce their NPL ratios to no more than 10 per cent by the end of December 2026
The Second Deputy Governor acknowledged that considerable work remained to achieve the regulatory target, particularly given the deterioration recorded by savings and loans companies.
“So, there is real work ahead of us in this last quarter to bring this in line with the regulatory expectation,” she said.
The proposed directive is expected to complement existing supervisory measures aimed at improving asset quality and strengthening credit risk governance across the financial sector.
Asante-Asiedu noted that the Bank of Ghana had already issued a 2025 Notice on Non-Performing Loans, which established supervisory expectations concerning credit risk governance, prudential limits for NPL ratios and remedial measures targeting wilful defaulters.
The new directive is intended to reinforce those measures by requiring financial institutions to establish stronger credit management systems and exercise more effective oversight throughout the lending cycle.
Under the proposed framework, institutions would be expected to strengthen their procedures for evaluating borrowers, administering loans, monitoring repayment performance and pursuing recovery where customers default.
The regulatory approach is aimed at ensuring that credit risks are identified and managed early, rather than allowing unpaid loans to accumulate and undermine the financial health of lending institutions. The announcement signals the Bank of Ghana’s continued emphasis on improving lending discipline and ensuring that financial institutions maintain sound credit portfolios.
Beyond credit risk management, Ms Asante-Asiedu said the Bank of Ghana was undertaking broader reforms of the savings and loans and microfinance sub-sectors.
She acknowledged the important role these institutions play in providing financial services to young people, women and micro, small and medium-sized enterprises (MSMEs), many of whom may have limited access to conventional banking services.
The institutions have also supported business development, employment creation and economic activity by extending credit to individuals and enterprises that are often overlooked by traditional banks. However, she stressed that institutions performing such an important role must have the financial strength, governance structures and operational capacity required to sustain their activities.
As part of the reforms, the existing Tier 1 to Tier 4 classification system will be replaced by four categories: Microfinance Banks, Community Banks, Credit Unions and Last Mile Providers.
Under the proposed arrangement, existing savings and loans companies may transition into Microfinance Banks, which will operate as deposit-taking institutions serving MSMEs, groups and individuals.
The restructuring is intended to improve regulatory consistency, reduce opportunities for regulatory arbitrage and ensure that institutions operating within the same category are subject to comparable standards.
The Bank of Ghana also expects boards and management teams to demonstrate the necessary professional competence, expertise and ethical standards required to oversee financial institutions effectively.
About the Author